The Conflict Nobody Wants in the New Year: Family Estate Disputes

17 December 2025

A new year is often a time for reflection, resolutions, and setting better foundations for the future. It’s also a moment when many people take stock of what truly matters—family, security, and peace of mind. But for families left without a clear estate plan, the start of a new year can quickly become a season marked not by hope, but by conflict.


While you may envision your loved ones supporting one another after you're gone, what actually happens without a plan is often far different. Instead of unity, families can experience confusion, resentment, and long-lasting disputes.


The Chaos Nobody Expects


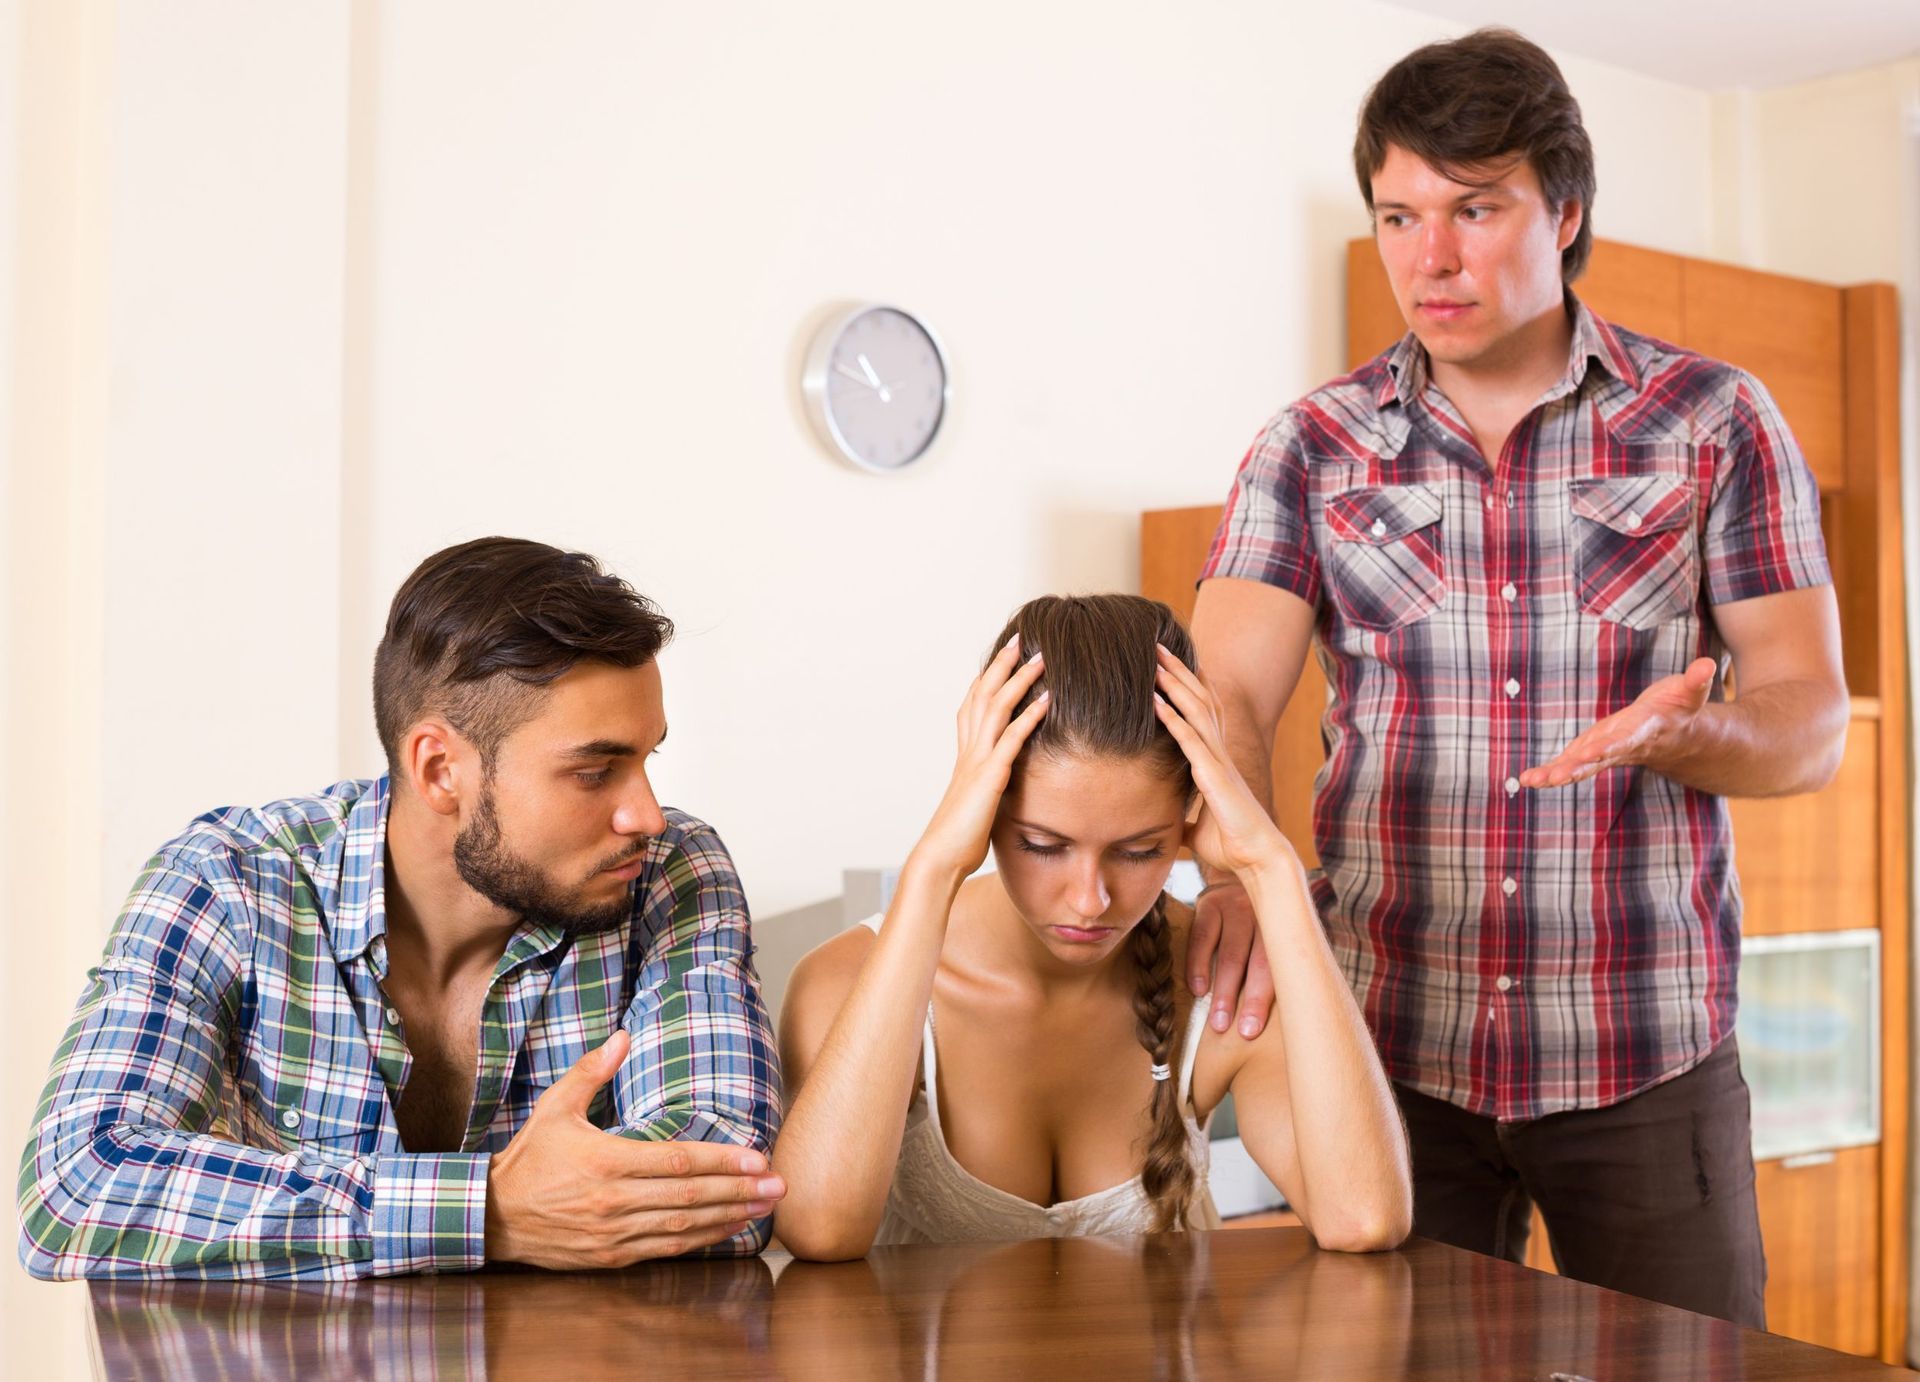
When someone dies without clear instructions, there are no rules, no guidance, and no agreement about who gets what. Instead of honoring your wishes, your family is left to interpret them—often very differently.


The results?

  • Multiple people claiming the same sentimental items
  • Deep disagreements about “who deserves what”
  • Old wounds and family dynamics resurfacing
  • Alliances forming and siblings growing distant
  • Spouses and children from prior relationships clashing
  • Costly court battles over who should be in charge


Without a plan, the state’s default laws take over, and the person who steps forward first—not necessarily the person you would have chosen—may gain control.
  • Slide title

    Write your caption here
    Button

When “Stealing” Becomes Real

In the absence of instructions, family members may rush to claim personal property, assuming their memories or verbal conversations will be honored. But without documentation, those promises are meaningless.


What starts as “I thought Mom wanted me to have this” becomes:

  • “She took more than her fair share.”
  • “Dad told me he promised that to me.”
  • “Why does the spouse get everything?”
  • “Why are they making decisions when they weren’t even around?”


These aren’t small disagreements—they’re fractures that can divide a family for generations.

Create Clarity Instead of Conflict


At my firm, we don’t just prepare documents—we help you create a plan your family can actually follow with confidence.


Through our Life & Legacy Planning Session, we help you:

  • Understand what you own and what it’s worth
  • Decide exactly who should receive what and why
  • Protect sentimental items so they go to the right people
  • Choose the right person to be in charge
  • Prevent court involvement, delays, and unnecessary costs
  • Ensure your loved ones can honor your wishes without stress or disagreement


Most importantly, we help you have meaningful conversations now, while you can explain your intentions and keep the peace long before conflict can arise.

Start the Year by Giving Your Family Peace of Mind

While many families begin the year with resolutions, you can begin it with something far more meaningful: clarity, protection, and a legacy your loved ones can carry forward without conflict.


If you’ve ever worried about what might happen if your family had to “figure things out,” take this as your sign.


📞 Schedule your complimentary 15-minute Discovery Call today and give your family the gift of peace this year—and every year to come.
  • Slide title

    Write your caption here
    Button
by Paul Suh • 7 October 2026
Learn how a pet trust can protect your pet’s future with a trustee, caregiver, funding, care instructions, and final wishes.
by Paul Suh • 1 October 2026
Learn five risks of leaving an outright inheritance and how a protective trust may help safeguard your children’s inheritance for the future.
by Paul Suh • 22 September 2026
Your IRA trust may need a 2026 review. Learn how SECURE Act rules, taxes, and beneficiary designations can affect your family's inheritance.
17 September 2026
You did it. You made a will. Maybe you've been meaning to get it done for years, or maybe something finally prompted you to take that important step. Either way, you now have something in place to tell your family and the court what you want to happen to your assets when you die. That's worth celebrating. But here's what I want you to know: making a will is the beginning of estate planning, not the end. A will doesn't address several important pieces, and overlooking them can leave your family with unnecessary court involvement, confusion, or financial headaches. If you already have a will, this is the checklist I recommend reviewing next. First, Understand What You Actually Signed A will is a legal document that tells a court what you want to happen to your assets after you die. That's the scope of it. It does not keep your family out of court. In most states, assets that pass through a will must go through probate, which is a public process that can take months, cost thousands in fees, and freeze your assets while it's happening. A will also only controls what's in it, not what you said. If you told someone you were leaving them your car and it isn't reflected in the document, that person may contest the will in court. Will contests are more common than most people realize, and even unsuccessful ones add cost, delay, and family conflict to an already difficult time. A will also does not control assets that have their own beneficiary designations: your retirement accounts, your life insurance, your bank accounts with transfer-on-death designations. Those pass outside your will entirely, by whatever name is on the form you filled out, sometimes years ago. And a will does nothing if you're incapacitated rather than dead. If you're in an accident and can't make decisions for yourself, your will doesn't activate. Your family may have no legal authority to manage your finances or make medical decisions without going to court first. The bottom line: A will is not a complete plan. Here's what building the rest of it actually looks like. Step 1: Your Beneficiary Designations May Already Be Overriding Your Will Most people don't realize this when they sign their will: an entirely separate set of documents already controls who gets a significant portion of their assets. Those documents are your beneficiary designation forms, and they operate completely outside of your will. Here is the part that matters. When your will conflicts with a beneficiary designation, the form wins. Every time. A judge does not have the authority to override it. Your will does not have the authority to override it. Whoever is named on that form gets the money. What I see most often: a former spouse still named on a retirement account. A parent who has since passed away. A child named directly as a beneficiary, which means that money is now subject to court-supervised guardianship until they turn 18, regardless of what your will says about how you wanted it managed. Every retirement account, life insurance policy, and bank account with a transfer-on-death designation needs to be reviewed. Each one needs a named primary beneficiary and a contingent beneficiary that reflects your family as it actually is today, not as it was the first week of your first job. Key takeaway: Your will does not control your beneficiary designations. Your beneficiary designations control themselves. Reviewing every form is one of the first things I walk through with every family in a Life & Legacy Planning® Session, because it is one of the most common places where an otherwise solid plan falls apart. Step 2: Find Out Whether Your Trust Is Actually Funded If you received a trust along with your will, ask one specific question: Are my assets actually in the trust? A trust only controls what is inside it. Signing a trust document creates a legal container. Transferring your assets into that container, which is called funding the trust, is a separate step that many families never complete. If your house, bank accounts, and investment accounts are still titled in your name rather than your trust's name, they will go through probate regardless of what the trust says. In my experience, unfunded trusts are one of the most common estate planning failures I encounter. Families pay for a trust, assume their estate is protected, and then their loved ones end up in probate court anyway because no one ever transferred the assets. The trust document is sitting in a folder. The assets never made it in. If you don't know whether your trust is funded, ask. If it isn't, funding it is the next priority. A trust you signed but never funded offers no more protection than no trust at all. Funding is not automatic. It has to be done deliberately, often with help.
by Paul Suh • 8 September 2026
Malcolm-Jamal Warner’s estate dispute highlights why estate planning requires more than documents. Learn how follow-through can protect your family.
by Paul Suh • 1 September 2026
Learn how guardianship works, when it becomes necessary, and how proper estate planning may help your family avoid costly court proceedings.
by Paul Suh • 25 August 2026
Learn how to encourage friends and family to create an estate plan with compassionate conversation starters that protect the people they love.
by Paul Suh • 18 August 2026
If your baby was born on or after January 1, 2025, the federal government has set aside $1,000 for your child. The account is available now. Contributions opened on July 4, 2026. And most families have not yet taken the step to claim it. The account is called a Trump Account. It was created by the One Big Beautiful Bill Act, signed into law in 2025, and it is one of the most significant new financial tools for young families in years. A seed investment that grows tax-advantaged for up to 18 years can become something meaningful by the time your child is ready to use it. Here is what you need to know, and what you should do next. What Is a Trump Account? A Trump Account is a tax-advantaged investment account created for a child. For every U.S. citizen born between January 1, 2025 and December 31, 2028, the federal government has committed to making a one-time $1,000 deposit, provided the child has a valid Social Security number. Beyond that government seed contribution, parents, grandparents, and other family members can contribute up to $5,000 per year. Before making personal contributions beyond claiming the $1,000 deposit, it's worth a call with your attorney first. There are unsettled regulatory questions about the gift tax treatment of family contributions that are still being worked out, and the right answer for your family depends on your specific situation. Employers can contribute up to $2,500 per year through a qualified written plan. If you own your own business, that means you could potentially contribute both as a parent and as an employer, for a combined $7,500 per year in additions to the account. The government's $1,000 does not count against either limit. The account is structured as a type of individual retirement account for the child. The account grows through stock market returns on a tax-deferred basis, meaning no taxes on the growth while the funds are invested, but ordinary income tax applies when distributions are eventually taken. The funds cannot be withdrawn before the child turns 18. At 18, the account converts to an IRA the young adult controls directly, though distributions before age 59½ are subject to income tax and a 10% early withdrawal penalty. That 18-year window is significant: a $1,000 deposit growing at a modest 7 percent average annual return becomes roughly $3,400 at maturity, without any additional contributions. Add even moderate contributions from family members over those years and the account can represent a meaningful head start. How the account is invested matters, and that is an active decision you make when you open it. Trump Accounts are not limited to babies born in the 2025 to 2028 window. Any child age 17 or younger with a valid Social Security number can have an account opened on their behalf. The free $1,000 pilot contribution, however, is only available for children born in that four-year window. The bottom line: A Trump Account is a federally seeded, tax-advantaged investment account for your child. The $1,000 is yours to claim. The contributions you add on top grow alongside it for up to 18 years. How to Open One  To open a Trump Account, families can file a one-page Form 4547 with the IRS or use the online portal at TrumpAccounts.gov. Contributions may begin as of July 4, 2026. The form walks through basic information about the child, including their Social Security number. If your child does not yet have a Social Security number, you will need to obtain one before completing the filing. To claim the government's $1,000 pilot contribution, you must make an affirmative election on the form: check the box in Part III, line 7. That election is what triggers the deposit. The account can be open and active without it, but without that election, no pilot contribution follows even though the account is up and running.
by Paul Suh • 11 August 2026
What if your spouse won’t engage in estate planning? Learn why it happens, what’s at risk, and steps you can take now to protect your family.
by Paul Suh • 4 August 2026
What happens to debt after death? Learn which debts pass to heirs, which don’t, and how families can avoid costly mistakes.